Tax Services
What Does Your Business Need Ready for Tax Preparation?
 By Maya Slivkov · · 6 min read
By Maya Slivkov, Tax Strategist & Founder · Last updated November 2026
Tax preparation for a small business starts long before your preparer opens a return. What you bring to the table — reconciled accounts, clean records, organized payroll filings — determines how much of their time goes to your return versus cleaning up what should have been done months earlier. Getting ahead of that is the job.
What clean books actually do for tax preparation
The connection is direct: a preparer who opens clean, reconciled books files faster and misses less. Per QuickBooks’ Entrepreneurship in 2025 research, 34% of business owners have made errors when filing taxes — most of those errors trace back to books that were incomplete or inconsistently categorized before the preparer ever saw them.
Clean books do three specific things in tax preparation. They let the preparer verify figures quickly instead of reconstructing them. They surface every deductible expense rather than only the ones that made it into clean categories. And they give the preparer the documentation needed to support deductions if the IRS asks — receipts, invoices, and transaction records that match what’s on the return.
The inverse is also true. A preparer who inherits twelve months of unreconciled accounts charges their hourly rate to do work that your bookkeeping should have handled. CPA hourly rates typically run $150–$500 per hour. That’s the real cost of unfinished books at filing time — not just a delayed return.
Getting your records organized
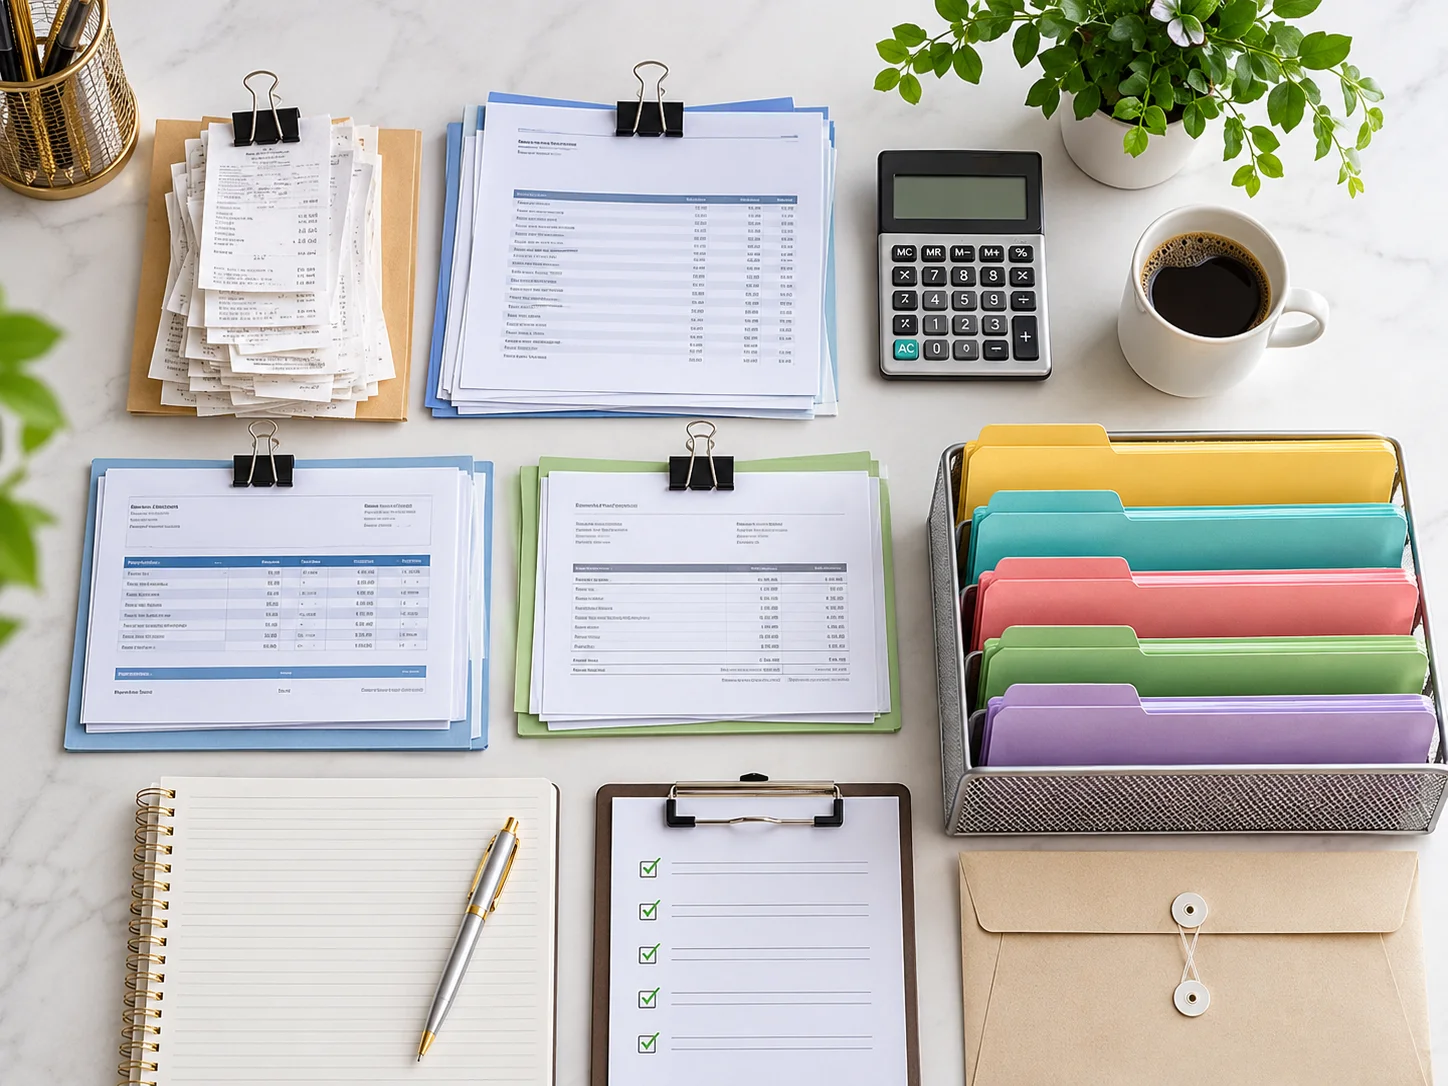
There’s no universal checklist that applies to every business, but most small businesses need the same core categories in order before tax preparation starts.
Reconciled accounts and financial statements
Every bank account and credit card should be reconciled through December 31. That means every transaction matches a statement, nothing is floating unclassified, and your profit and loss and balance sheet reflect actual results. These are the numbers your preparer builds the return from.
Payroll filings and contractor records
Payroll needs to be fully filed before year-end closes. W-2s go out to employees by January 31. For 2026 tax years, 1099-NEC filings cover any contractor paid $2,000 or more during the year — the threshold increased from $600 for payments made in 2026. If those filings aren’t in order, your preparer has to work around them. That delays everything else.
Asset records and owner equity
Fixed-asset schedules should reflect any equipment purchased or disposed of during the year. Depreciation elections — including Section 179 and bonus depreciation — need clean asset records to run correctly. Owner equity documentation (contributions, draws, ownership changes) also needs to be current, particularly for S-corps and partnerships whose returns are due March 15.
Starting earlier than you think
Most businesses treat tax preparation as an April problem. The ones that handle it well treat it as a November and December problem.
The practical reason is deadlines. S-corporations and partnerships file by March 15 — not April 15. That’s one full month earlier than most owners realize. It means December books need to be fully closed and handed off by mid-February at the latest. Waiting until March to reconcile November and December creates a crunch that can’t be resolved without paying for rush prep work.
There’s also a planning angle. November and December are the last months where tax decisions can still be made: equipment purchases that qualify for Section 179, year-end owner distributions, retirement contributions. Once January 1 passes, most of those options close. Good tax preparation isn’t just filing — it starts with decisions made while the year is still alive. The quarterly estimated tax framework is the structure those decisions sit inside.
The handoff: how bookkeeper and preparer divide the work
The two roles are distinct and shouldn’t overlap. The bookkeeper closes the year — reconciles accounts, finalizes payroll, produces clean financial statements, and delivers a year-end package the preparer can open and work from. The preparer takes that package, applies tax law, prepares the returns, and files them.
When that division works, the preparer is spending time on tax strategy and return accuracy, not data entry. When it breaks down — usually because books aren’t closed when the preparer needs them — the preparer either waits or charges hourly to do catch-up work outside their core scope.
For a detailed look at how the bookkeeper and accountant hand off at year end — thebookkeepingcomp.org/bookkeeper-vs-accountant/ — that post covers the specific documents involved and what clean delivery looks like in practice.
The cost of unfinished books at filing time
Unfinished books at tax time don’t just slow things down. They create specific, quantifiable problems.
The most direct cost is the cleanup fee. If reconciliations are three months behind, your preparer charges their standard rate to close them. That’s money spent on work that happened because books weren’t maintained — not on return preparation itself.
The second cost is missed deductions. Expenses that weren’t properly categorized during the year don’t always surface in an end-of-year review. A preparer working quickly through disorganized records will catch the obvious ones. They’ll miss the edge cases.
The third cost is timeline pressure. A rushed return is more likely to need an amendment later. Extensions are available — Form 7004 gives S-corps and partnerships an automatic six-month extension, Form 4868 covers sole proprietors and single-member LLCs — but an extension extends the filing deadline, not the payment deadline. Tax owed is still due on the original date.
Questions about where your books stand heading into filing season? The tax preparation services page — thebookkeepingcomp.org/tax-preparation-vancouver-wa/ — covers how The Bookkeeping Company approaches year-end preparation and what that process looks like from the first conversation.
Frequently Asked Questions
What does a business need to have ready before tax preparation starts?
The core set: reconciled bank and credit card accounts through December 31, finalized payroll filings (W-2s and 1099s), fixed-asset and depreciation schedules, and equity documentation for any ownership changes during the year. S-corps and partnerships also need a completed Schedule K-1 for each owner. The fuller the year-end package, the less time — and cost — goes to cleanup before the return is built.
How much does clean bookkeeping reduce the tax bill of work?
The direct saving is in preparer hours. CPA rates run $150–$500 per hour, and a preparer working from disorganized records typically spends several hours more per return than one working from clean books. Beyond the hourly savings, clean books surface deductions that incomplete records miss. The combined effect — fewer prep hours and more complete deductions — means the return costs less and returns more.
When should preparation actually begin?
For most businesses, November is the right time to start. That’s when year-end decisions still have tax impact — equipment purchases, owner distributions, retirement contributions — and when December’s close is close enough to plan around. For S-corps and partnerships with a March 15 deadline, books need to be fully closed and handed to the preparer by mid-February. Waiting until April usually means paying more for rushed prep work.
What happens if the books are not finished in time?
The preparer either waits or charges their hourly rate to do the catch-up work. Most choose the latter. The result is a higher prep bill, a delayed filing, and more exposure to errors from working quickly through messy records. Extensions buy time on the filing date — not on the tax payment. If the return is extended but tax isn’t paid by the original deadline, penalties and interest accrue from that date forward.
Who does what between the bookkeeper and the tax preparer?
The bookkeeper closes the year: reconciles all accounts, finalizes payroll, produces financial statements, and prepares the year-end document package. The tax preparer takes that package, applies current tax law, prepares and files the returns. When both roles do their jobs cleanly, the preparer is never doing bookkeeper work and the bookkeeper is never trying to make tax decisions. That division produces faster filings, lower total costs, and returns that are easier to defend.
The Bookkeeping Company
Vancouver, WA
Phone: (360) 524-9889
Tax strategy, bookkeeping, and tax preparation for small business owners and contractors nationwide.
This article is general information, not tax advice for your situation. Every case is different, and tax law changes.
Want to talk through your own numbers?
Book a 20-minute discovery call with Maya.
Book a discovery call