Payroll Services
Payroll Services: What’s Included for a Small Business
 By Maya Slivkov · · 7 min read
By Maya Slivkov, Tax Strategist & Founder at The Bookkeeping Company | Last updated: October 2026
Running payroll is one of the most deadline-driven tasks in a small business. Miss a deposit date and the penalty clock starts before anyone notices. Payroll services take it off the plate — but what’s included depends heavily on how the service is structured and which state you’re in.
What Is Actually Included in Payroll Services?
More than most owners realize. Issuing paychecks is the visible part. The work underneath — the tax withholding, the deposits, the filings, the year-end forms — is what a full payroll service actually covers.
What a full service handles: calculating wages and running direct deposit each cycle, withholding and depositing federal and state taxes on schedule, generating itemized pay stubs, and filing the quarterly returns. New hire reporting is usually bundled in too. Oregon requires that each new employee be filed with the Division of Child Support within 20 days of hire — a step most first-time employers miss until they’ve already missed it.
What doesn’t come with it: HR decisions, benefits administration, and the classification call on whether someone is an employee or a contractor. That last one shapes the entire payroll setup, so it’s worth settling before the first paycheck runs.
Oregon’s Withholding: One Difference Worth Knowing
Oregon has its own withholding certificate, Form OR-W-4. Without one on file for a new hire, the employer defaults to a flat 8% withholding regardless of the employee’s actual situation — and 8% almost never matches. In practice, adding it to the first-day packet alongside the I-9 takes two minutes and removes a W-2 argument in April.
Four rates: 4.75%, 6.75%, 8.75%, 9.9%. Most full-time Oregon employees are already sitting in the 8.75% bracket before the salary conversation starts. Per the QuickBooks 2026 Oregon payroll guide, that rate is why take-home pay questions in Oregon almost always start with the withholding table, not the gross offer.
Skip the books and the payroll numbers will be wrong at filing time. Our monthly bookkeeping services handle the job-level cost tracking, monthly reconciliations, and account closes that both payroll and tax prep run on.
Which Filings and Forms Come with Running Payroll?
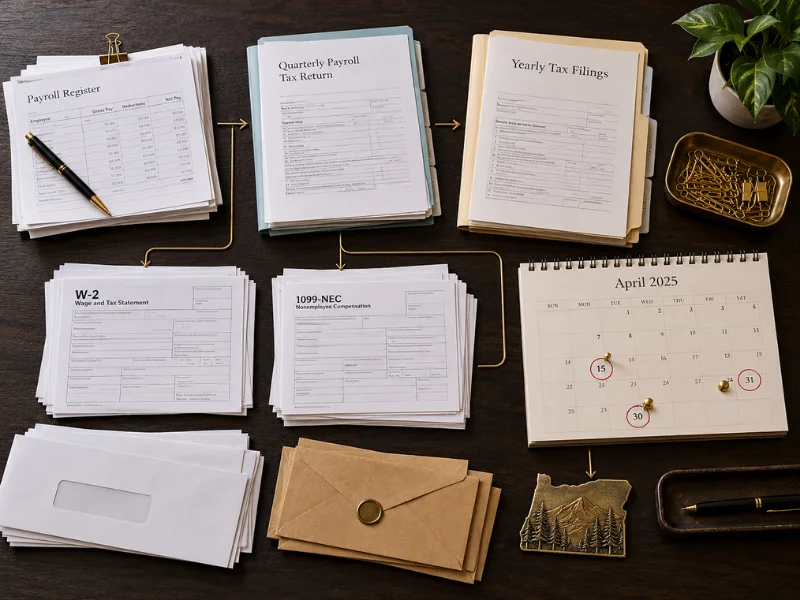
This is the part that surprises most first-time employers. Payroll doesn’t just generate paychecks — it generates a filing stack. Federal and state. Quarterly and annual. Each with its own deadline.
Federal Requirements
Form 941 files every quarter — covers income tax, Social Security, and Medicare withheld from employees. Form 940 comes around once a year in January for federal unemployment. W-2s go to employees and the IRS by January 31, with a W-3 transmittal to the Social Security Administration at the same time. Any contractor you paid $600 or more during the year gets a 1099-NEC, also due January 31.
Oregon State Requirements
Oregon runs everything through one combined quarterly return, Form OQ. UI contributions, Paid Leave Oregon, state income tax withholding, the statewide transit tax, and the Workers’ Benefit Fund assessment all go in together — one return, one due date.
UI is employer-only on the first $56,700 of wages per employee in 2026. New employers start at 2.4%, then move to an experience-based rate after a few years. The WBF assessment runs 1.8 cents per hour worked this year, rising to 2.4 cents from January 2027. Employer pays at least half; the rest gets withheld from the employee.
Paid Leave Oregon takes 1% of wages up to $184,500. Businesses averaging 25 or more employees pay 40% of that; employees cover 60%. Under 25, only the employee share goes in. Worth knowing: the headcount test includes staff in other states, even though contributions only apply to Oregon wages. Eight employees in Portland and twenty in California — large employer, Oregon Paid Leave rules apply.
TriMet and LTD also go into Form OQ if your people work inside those boundaries. TriMet covers the Portland metro area at 0.8237%; LTD covers Eugene–Springfield at 0.80%. Both are employer-paid on wages earned inside the district.
Year-end adds Form OR-WR — Oregon’s annual withholding reconciliation, filed electronically. A W-2 that turns out wrong after filing becomes a W-2c. Own the error early.
Employee vs. Contractor: Payroll Implications
The classification shapes the entire payroll setup. Oregon BOLI doesn’t look at what the contract says — it looks at how the work relationship actually runs.
How Oregon Decides
Oregon uses the “economic realities” test and industry-specific criteria. The factors: who directs the work, who sets the price and bears financial risk, and how integral the work is to the business. Per the HiveDesk 2026 Oregon labor law guide, construction and trades businesses face heightened scrutiny — the sector has historically seen high misclassification rates, and BOLI enforces it actively.
The Difference on the Payroll Side
Employee on payroll: full withholding every cycle, W-2 in January, Paid Leave contributions on both sides, employer FICA, UI tax, Oregon sick time accrual from day one.
Contractor paid directly: gross payment, no withholding, no employer-side taxes. If they cleared $600 in the year, a 1099-NEC goes out in January. That’s the whole filing obligation on that person.
The cost difference between the two setups is why misclassification happens. When BOLI catches it, the business owes the full unpaid employer tax stack — back UI, back Paid Leave, back employer FICA — plus penalties. Personal liability for the owner can come into it. On a public works project in Portland or Salem, one misclassified worker has pulled full payroll audits. In the trades, that’s not a rare outcome.
Year-End Payroll Closeout
January 31 is most of it, and several things land at once. W-2s go to employees and the IRS. The W-3 batch transmittal goes to the Social Security Administration alongside them. 1099-NECs go to any contractor who cleared $600 in the year. Form 940 for federal unemployment. Oregon’s Form OR-WR electronically to the DOR.
One thing specific to Oregon S-Corps: health insurance premiums for shareholders who are more than 2% owners go into W-2 wages. That’s a payroll setup decision made during the year — not something to reconstruct in December when the books are closed.
Our tax preparation services work from the payroll records directly. When the books come in already reconciled, the return is the easy part.
Bonus, Overtime, and Reimbursement Processing
Bonuses
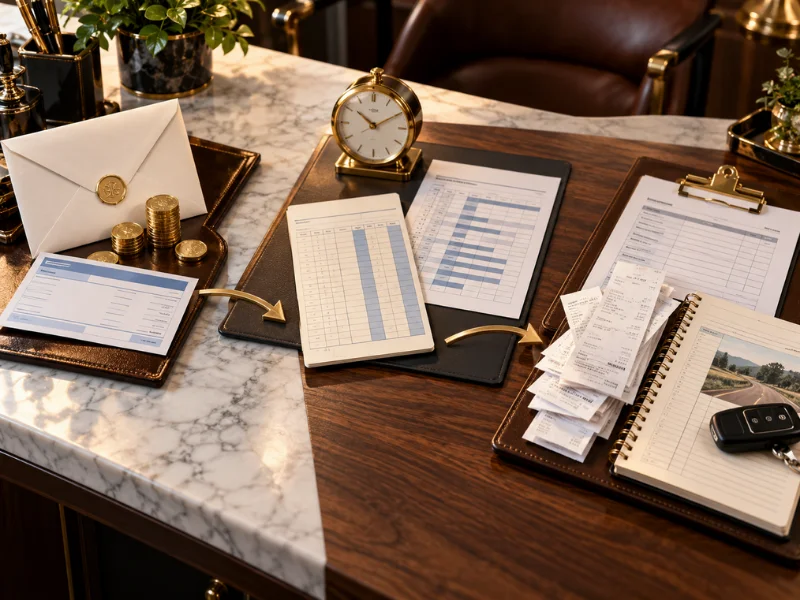
Bonuses are wages. They run through payroll and withholding applies — 22% federal at the supplemental rate, 8% Oregon state. That 8% is the same flat fallback that kicks in when no OR-W-4 is on file, which is worth knowing: a new employee without an OR-W-4 and a mid-year bonus can end up with withholding that’s off in two different directions.
Overtime
Weekly overtime kicks in at 40 hours for most roles. Manufacturing operations also carry a daily trigger — 10 hours in a day, with a 55-hour weekly cap unless the employee puts consent in writing for up to 60. General contracting usually stays outside that rule, but fabrication or production work can fall inside it. Check the role before setting up the payroll.
Expense Reimbursements
Reimbursements with a receipt, a documented purpose, and any unused amount returned aren’t wages. Nothing gets withheld, nothing goes on the W-2. A flat car allowance or tool allowance paid as a fixed amount with none of that documentation is treated as wages — withholding applies, and the amount shows up on the W-2 in January. Both arrangements are common in the trades. The setup call is easier to get right at the start.
Frequently Asked Questions
What is actually included in a payroll service?
Pay runs, tax withholding, employer deposits, direct deposit, pay stubs, quarterly filings — that’s the baseline. In Oregon a full setup also handles Form OQ, Paid Leave contributions, and the WBF per-hour assessment. Year-end W-2s and 1099-NECs are typically bundled in, though some services add them separately. Confirm that before you sign on.
Which filings and forms come with paying employees?
More than most owners expect. Federal: Form 941 quarterly, Form 940 in January, W-2s and the W-3 to the SSA by January 31, 1099-NEC for any contractor who cleared $600. Oregon: Form OQ quarterly covers withholding, UI, Paid Leave, transit tax, and the WBF all in one return; Form OR-WR annually. New hire reports within 20 days of hire.
What happens at year end?
January 31 is when it all lands. W-2s to employees and the IRS. W-3 to the Social Security Administration. 1099-NECs for contractors who cleared $600. Form 940 for federal unemployment. Oregon Form OR-WR electronically. One S-Corp note: shareholders who are more than 2% owners need health insurance premiums included in W-2 wages — a setup call to make during the year, not in December.
Employee or contractor: what changes for the business?
Very different on the employer side. Employee: withholding every cycle, W-2 in January, employer FICA, UI tax, Paid Leave contributions on both sides, sick time accrual. Contractor: gross payment, 1099-NEC if they cleared $600, no employer-side taxes. Oregon BOLI doesn’t look at what the contract says — it looks at how the work actually runs. A wrong call carries back taxes, penalties, and in some situations personal liability for the owner.
How are bonuses, overtime, and reimbursements handled?
All three differently, and all three matter for the W-2. Bonuses run at the supplemental withholding rate — 22% federal, 8% Oregon. Overtime: 40-hour weekly threshold for most roles, plus a daily trigger in manufacturing at 10 hours. Expense reimbursements with documentation aren’t wages; a flat allowance with no accountability is. Getting those setup calls right early is much less work than sorting them out in January.
The Bookkeeping Company 18523 NE 65th St, Vancouver, WA 98682 (360) 524-9889 ★★★★★ 4.9 from 72 Google reviews Serving Clark County, Portland metro, Oregon statewide, and clients nationwide. All services delivered remotely through QuickBooks Online. |
Need help getting payroll set up or off your plate?
This article is general information, not tax advice for your situation. Every case is different, and tax law changes.
Want to talk through your own numbers?
Book a 20-minute discovery call with Maya.
Book a discovery call